C3.ai (AI) — Deep Dive
Prices as of the Mon 05 Oct 2026 close · data pulled 2026-10-06 07:31:00+00:00 · refreshed weekly · methodology
Not investment advice
Educational analysis built from public data (Yahoo Finance, Kenneth French Data Library) and explicit model assumptions. Numbers update automatically; the qualitative notes are dated.
Verdict: Reduce / Avoid — 3/8 checks pass
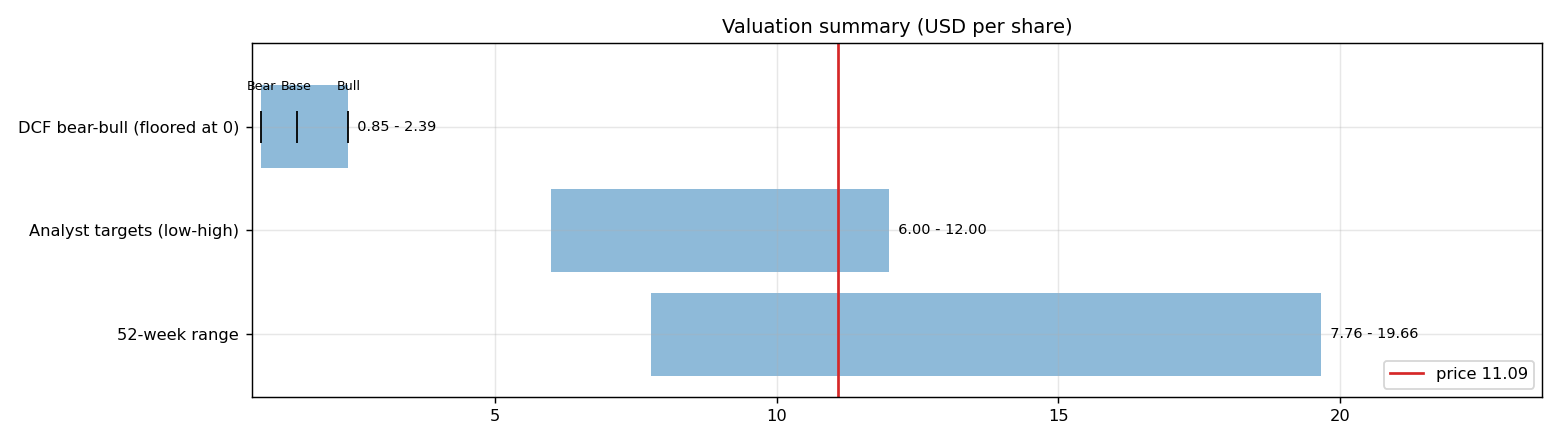
C3.ai is not yet free-cash-flow positive after stock compensation, with net cash of USD 0.6bn and consensus revenue of 0.2bn for FY2027 and 0.2bn for FY2028 (+10%). At USD 11.09 the market prices in 84% a year revenue growth after FY2028 (fading to 4%) at a 9% owner-FCF margin, or a 74% margin on the base growth path. The base-case DCF is USD 1.48 (-87%). Cash runway at the current burn: about 4.2 years.
| Check | Pass | Evidence |
|---|---|---|
| Valuation: base-case DCF at or above price | ❌ | base DCF USD 1 vs price USD 11 |
| Relative value: forward P/E at most 1.2x the peer median | ❌ | n/m FY2028E vs peer median 80.8x |
| Street: de-biased, shrunk analyst alpha > 0 (ch27) | ❌ | -12.7% |
| Momentum: 12-1 month return > 0 (ch11) | ❌ | -40% |
| Trend: price above 200-day MA (ch12) | ✅ | +8% vs 200DMA |
| Not overbought: RSI(14) below 70 | ✅ | RSI 58 |
| Fundamentals: revenue growing and FCF positive | ❌ | revenue -25% y/y, TTM FCF -0.2bn |
| Balance sheet: net cash | ✅ | net cash 0.6bn |
Snapshot
| Metric | Value | Metric | Value |
|---|---|---|---|
| Price | USD 11.09 | Market cap | USD 1.7bn |
| Enterprise value | USD 1.2bn | Net cash | USD 0.6bn |
| 52-week range | 7.76 – 19.66 | From 52w high | -43.6% |
| Trailing P/E (GAAP) | n/m | Forward P/E FY2027 / FY2028 | n/m / n/m |
| PEG (FY+1 P/E ÷ EPS growth) | n/a | EV / TTM revenue | 5.0x |
| TTM revenue | USD 0.2bn | TTM FCF / after SBC | -0.2bn / -0.4bn |
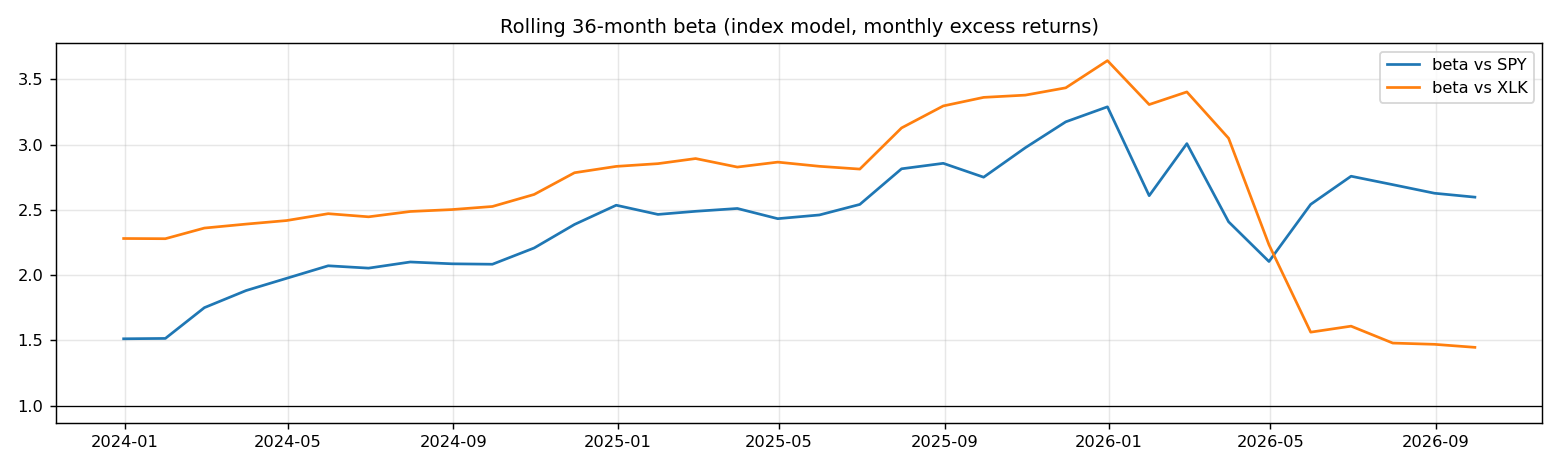
| Beta vs SPY (raw / Blume) | 2.09 / 1.73 | Realized vol 20d / 1y | 40% / 60% |
| Analysts / mean target | 10 / USD 8 (-25.2%) | Next earnings | n/a |
| Shares out (diluted proxy) | 0.157bn | Short interest (% float) | 28.6% |
| Sector ETF benchmark | XLK | Cash runway (cash ÷ FCF burn) | 4.2 years |
| Institutions / insiders | 64% / 8.13% | Dividend | none |
1. Price over time
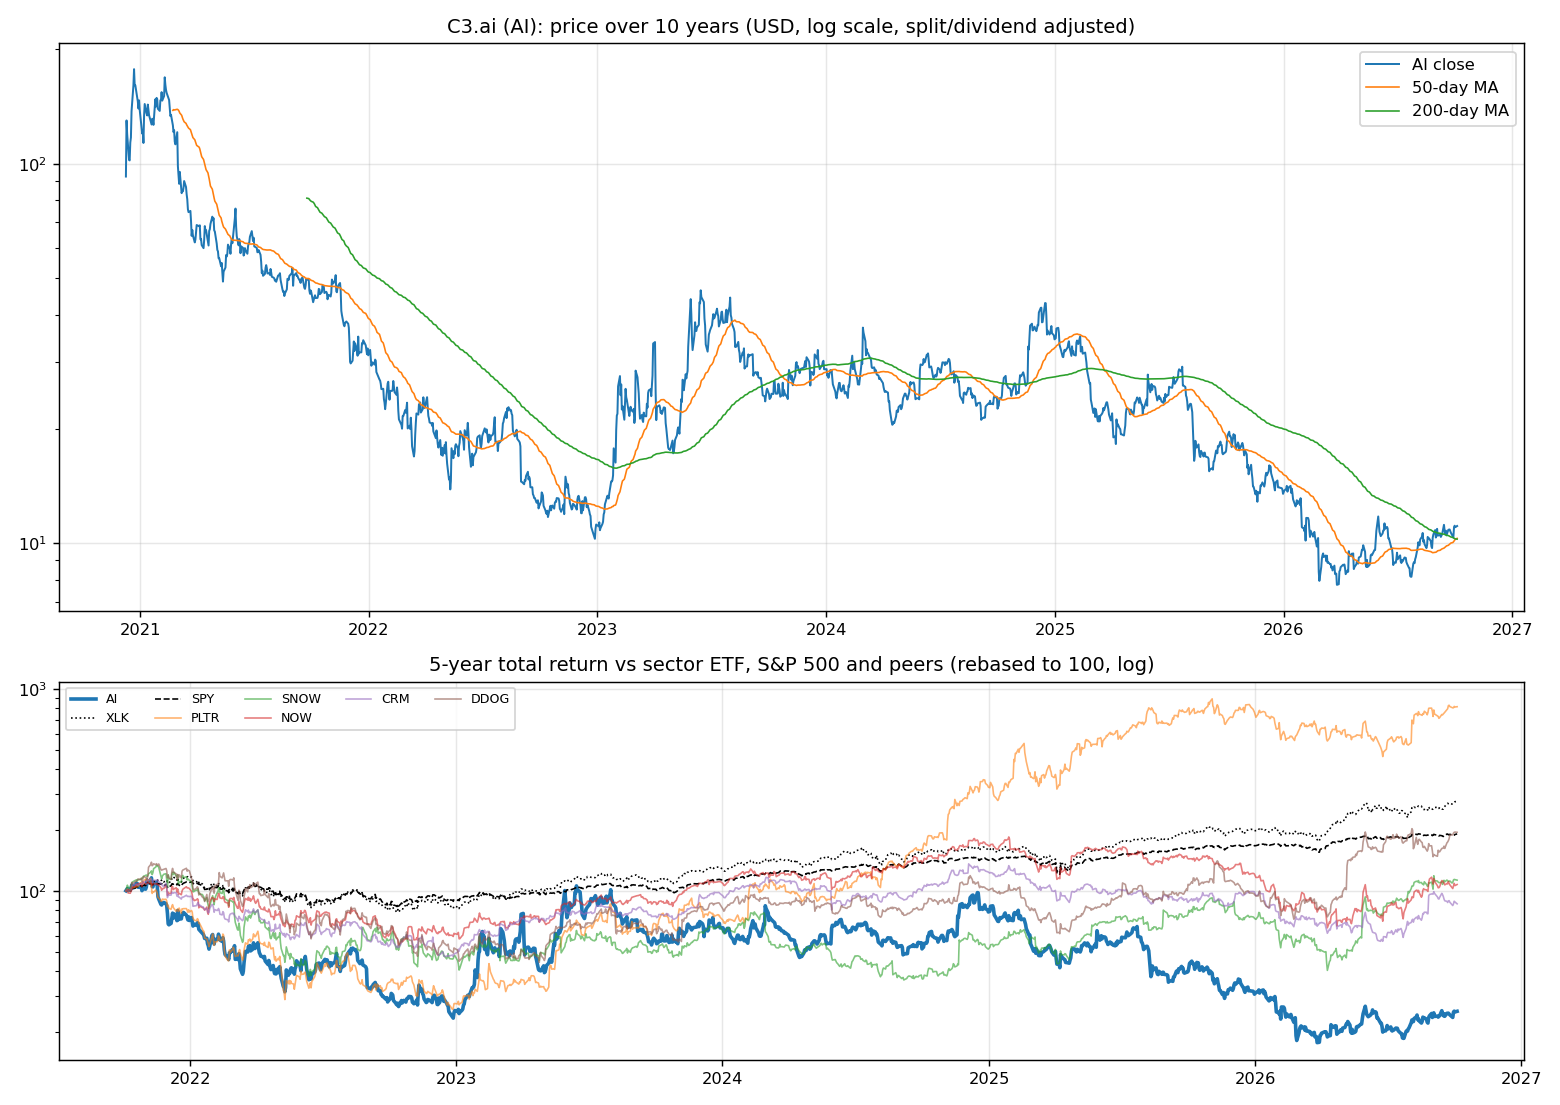
| Ticker | 1M | 3M | 6M | YTD | 1Y | 3Y | 5Y | 10Y | 10Y CAGR |
|---|---|---|---|---|---|---|---|---|---|
| AI | +6% | +20% | +26% | -18% | -42% | -55% | -75% | n/a | n/a |
| XLK | +7% | +10% | +47% | +40% | +42% | +143% | +178% | +834% | 25.0% |
| SPY | +1% | +3% | +18% | +15% | +17% | +87% | +91% | +321% | 15.5% |
| PLTR | +9% | +43% | +28% | +7% | +9% | +1040% | +716% | n/a | n/a |
| SNOW | +1% | +29% | +127% | +55% | +44% | +112% | +13% | n/a | n/a |
| NOW | -4% | +26% | +33% | -11% | -25% | +21% | +7% | +757% | 24.0% |
| CRM | -11% | +39% | +25% | -13% | -4% | +13% | -14% | +242% | 13.1% |
| DDOG | +30% | +8% | +137% | +103% | +82% | +193% | +95% | n/a | n/a |
Largest one-day moves in the last 5 years: 04 Apr 2023 -26.3%, 11 Aug 2025 -25.6%, 03 Mar 2023 +33.6%, 30 May 2023 +33.4%, 29 Feb 2024 +24.5%.
2. Return and risk (ch.5)
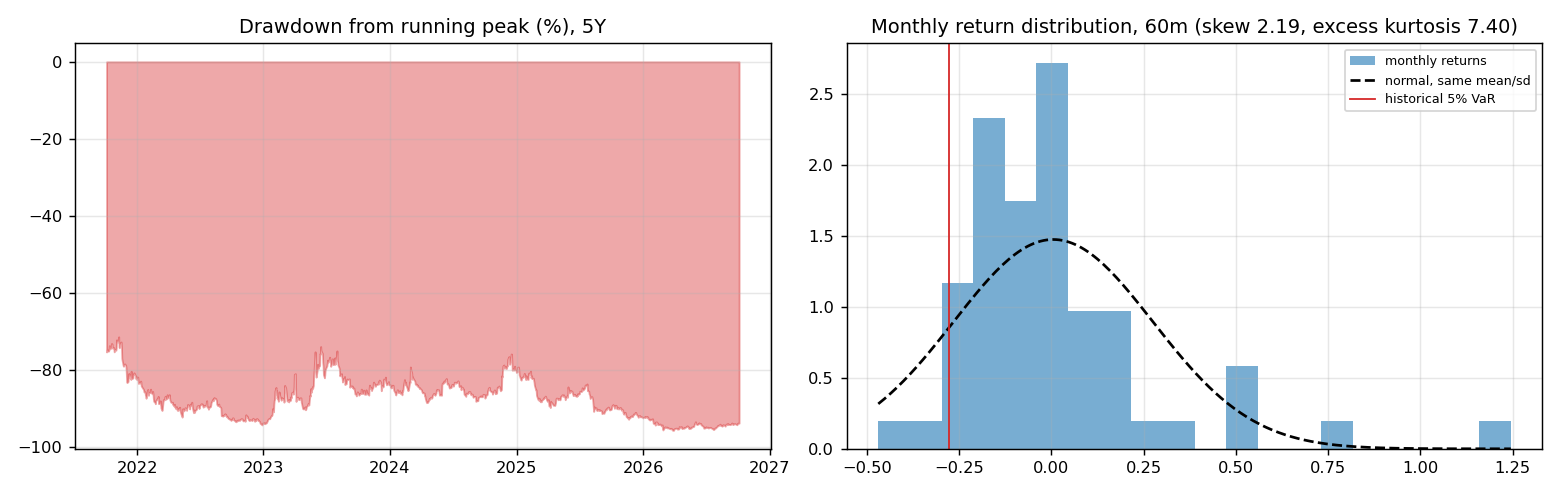
Statistics use the 60 complete months to Sep 2026.
| Statistic | Value | What it means |
|---|---|---|
| Arithmetic mean (annualized) | 6.1% | Expected one-period return if the past repeats |
| Geometric mean (CAGR) | -25.0% | What a buy-and-hold investor actually earned; the gap ≈ σ²/2 is volatility drag |
| Standard deviation (annualized) | 93.7% | 6.0× the S&P 500's 15.7% |
| Skewness / excess kurtosis | 2.19 / 7.40 | Right-skewed, fat tails vs normal |
| 5% monthly VaR: historical / normal | -27.8% / -44.0% | One month in 20 loses at least this much |
| 5% monthly expected shortfall | -35.2% | Average loss in that worst 5% of months |
| Sharpe ratio (S&P 500) | 0.03 (0.67) | Excess return per unit of total risk |
| Sortino ratio | 0.05 | Excess return per unit of downside risk |
| Max drawdown, 5y | -95.6% (trough Mar 2026) | Currently -93.8% from the peak |
3. Index model, CAPM and factors (ch.8–10)
| Regression (60m excess returns) | Alpha (ann.) | t(α) | Beta | t(β) | R² | Residual σ |
|---|---|---|---|---|---|---|
| vs SPY | -19.4% | -0.48 | 2.09 | 2.83 | 0.12 | 87.7% |
| vs XLK | -34.4% | -0.91 | 1.91 | 4.27 | 0.24 | 81.6% |
- Risk decomposition (ch.8): systematic variance β²σ²(M) = 10.8% vs firm-specific σ²(e) = 76.9%, so 12% of the risk is market-driven and 88% is diversifiable.
- CAPM required return (ch.9): k = r_f + β × MRP = 4.02% + 2.09 × 5.5% = 15.5% (Blume-adjusted β 1.73 → 13.5%, used as the DCF discount rate).
- Historical alpha of -19.4% a year has a t-stat of -0.48: not statistically distinguishable from zero (ch.11: past alpha is a weak guide).
- Fama-French 5 factors + momentum (ch.10, 67 months to Jul 2026): R² 0.38, alpha +11.0% (t 0.32). Loadings: Mkt-RF +0.99 (t 1.5), SMB +1.01 (t 0.9), HML -2.42 (t -2.4), RMW -1.50 (t -1.5), CMA -1.04 (t -0.8), Mom -1.11 (t -1.5). The loadings describe a small-cap, growth, low-profitability return profile (SMB > 0 small-cap, HML < 0 growth, RMW < 0 weak profitability, CMA < 0 aggressive investment).
4. Portfolio fit: allocation and diversification (ch.6–7)
Correlation of monthly returns with AI (60m): XLK 0.49, SPY 0.35, PLTR 0.72, SNOW 0.36, NOW 0.50, CRM 0.53, DDOG 0.44.
- A 50/50 mix with SPY would have had volatility of 50.1% vs 54.7% for the weighted average of the two, a diversification benefit because ρ = 0.35 < 1.
- Optimal risky share y* = [E(r) − r_f] / (A·σ²), holding AI alone against T-bills (σ = 93.7%):
| Risk aversion A | y* with CAPM E(r) | y* with E(r) + Street α |
|---|---|---|
| 2 | 7% | -1% |
| 3 | 4% | -0% |
| 4 | 3% | -0% |
| 6 | 2% | -0% |
Even a risk-tolerant investor would put only a modest share in a single stock this volatile. Ch.7–8 say the efficient choice is the market portfolio plus a Treynor-Black tilt (section 9), not a concentrated position.
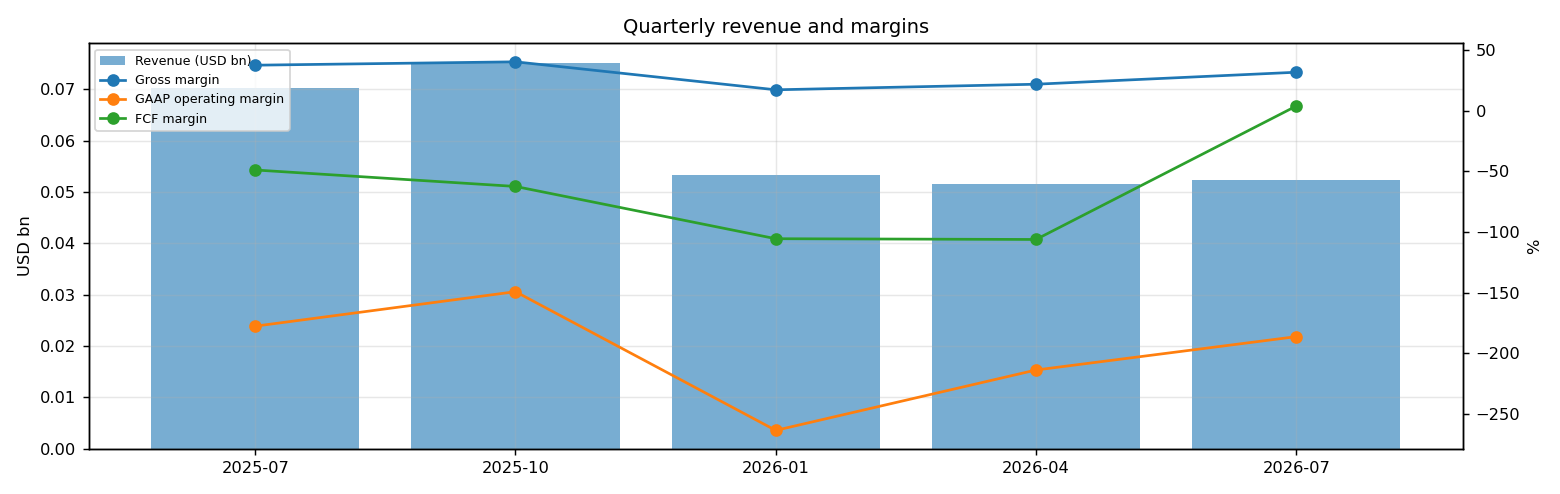
5. Financial statements: quality of earnings (ch.19)
| Quarter | Revenue | Q/Q | Gross m. | Op. m. (GAAP) | Net m. | R&D % | SBC % | Diluted EPS | FCF | FCF m. | DSO (days) | DIO (days) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2025-07 | 0.1bn | n/a | 37.6% | -177.7% | -166.2% | 92.0% | 92.2% | -0.86 | -0.03bn | -48.8% | 148 | n/a |
| 2025-10 | 0.1bn | +7% | 40.4% | -149.2% | -139.3% | 77.7% | 91.6% | -0.75 | -0.05bn | -62.4% | 165 | n/a |
| 2026-01 | 0.1bn | -29% | 17.3% | -263.6% | -250.4% | 110.4% | 142.5% | -0.94 | -0.06bn | -105.5% | 211 | n/a |
| 2026-04 | 0.1bn | -3% | 21.9% | -213.8% | -224.0% | 91.6% | 105.0% | -0.79 | -0.05bn | -106.1% | 177 | n/a |
| 2026-07 | 0.1bn | +2% | 31.8% | -186.3% | -177.2% | 88.9% | 113.1% | -0.60 | 0.00bn | 3.9% | 164 | n/a |
- DuPont, TTM: ROE -61.3% = net margin -192.1% × asset turnover 0.26 × leverage 1.24. Net income is negative, so ROE is negative; the business is not yet earning its cost of equity.
- Cash conversion: TTM operating cash flow -0.2bn vs net income -0.4bn. The accruals ratio of -32.3% of assets is negative (cash earnings exceed accounting earnings), a sign of high-quality earnings.
- Stock-based compensation of 0.3bn TTM (111.1% of revenue) is a real cost to shareholders. The valuation below uses FCF after SBC (owner FCF margin -150.0%). Buybacks were n/a; share count changed +16.8% over the year.
- Operating leverage (ch.17): not meaningful: EBIT was negative or sales barely moved between the last two fiscal years.
6. Valuation (ch.18)
Multiples vs peers (Yahoo Finance, TTM and next-year; peers chosen by hand in config.json):
| Ticker | Fwd P/E | P/S TTM | EV/EBITDA | FCF yield | Rev. growth FY | Gross m. | EBIT m. | ROE TTM | Target upside |
|---|---|---|---|---|---|---|---|---|---|
| AI | -23.3x | 7.7x | -2.7x | 1% | -26% | 29% | -186% | -60% | -25% |
| PLTR | 80.8x | 73.9x | 167.5x | 0% | 93% | 85% | 47% | 38% | 3% |
| SNOW | 112.8x | 22.0x | -115.7x | 1% | 35% | 67% | -17% | -48% | 25% |
| NOW | 27.2x | 9.5x | 49.9x | 4% | 24% | 75% | 4% | 14% | 7% |
| CRM | 14.3x | 4.3x | 17.1x | 9% | 11% | 77% | 21% | 19% | 23% |
| DDOG | 92.9x | 25.0x | 1152.6x | 1% | 36% | 80% | 1% | 5% | 4% |
| Peer median | 80.8x | 22.0x | 49.9x | 1% | 35% | 77% | 4% | 14% | 7% |
Growth embedded in the price (PVGO). Next-year EPS is expected to be negative (USD -0.48), so the whole price is PVGO: it rests entirely on future profits that do not exist yet.
Constant-growth check. On TTM owner FCF, P = FCF₁/(k − g) implies a perpetual growth rate of 50.9%, above the 4% long-run nominal-GDP ceiling the book recommends for g.
Scenario DCF (owner FCF, k = 13.5%, terminal g = 4%). The revenue path is FY2027 (0.2bn), then the FY2028 low/avg/high estimate, then growth that fades linearly to 4% over 8 years. Owner-FCF margin ramps from today's -150.0% to the scenario margin over 5 years. Scenario assumptions are generic (derived from consensus growth and today's owner-FCF margin).
| Scenario | FY2028 revenue | Growth after | Owner-FCF margin | FY2036 revenue | Terminal value share | Value / share | vs price |
|---|---|---|---|---|---|---|---|
| Bear | 0.2bn | 4% | 3% | 0bn | n/a | USD 0.85 | -92% |
| Base | 0.2bn | 8% | 9% | 0bn | n/a | USD 1.48 | -87% |
| Bull | 0.3bn | 12% | 14% | 1bn | n/a | USD 2.39 | -78% |
Reverse DCF: what today's price assumes. On the base revenue path the price requires a steady-state owner-FCF margin of 74%. At the base 9% margin it requires 84% growth after FY2028, or a discount rate of 5.3% (vs the model's 13.5%).
Sensitivity: base revenue path, value per share by discount rate (rows) and steady-state owner-FCF margin (columns).
| k \ margin | 5% | 7% | 9% | 10% | 12% |
|---|---|---|---|---|---|
| 10.5% | 1.09 | 1.55 | 2.01 | 2.24 | 2.71 |
| 11.5% | 1.00 | 1.39 | 1.78 | 1.98 | 2.37 |
| 12.5% | 0.95 | 1.29 | 1.63 | 1.79 | 2.13 |
| 13.5% | 0.93 | 1.23 | 1.52 | 1.67 | 1.96 |
| 14.5% | 0.93 | 1.19 | 1.45 | 1.58 | 1.84 |
| ## 7. Market efficiency and earnings reactions (ch.11) |
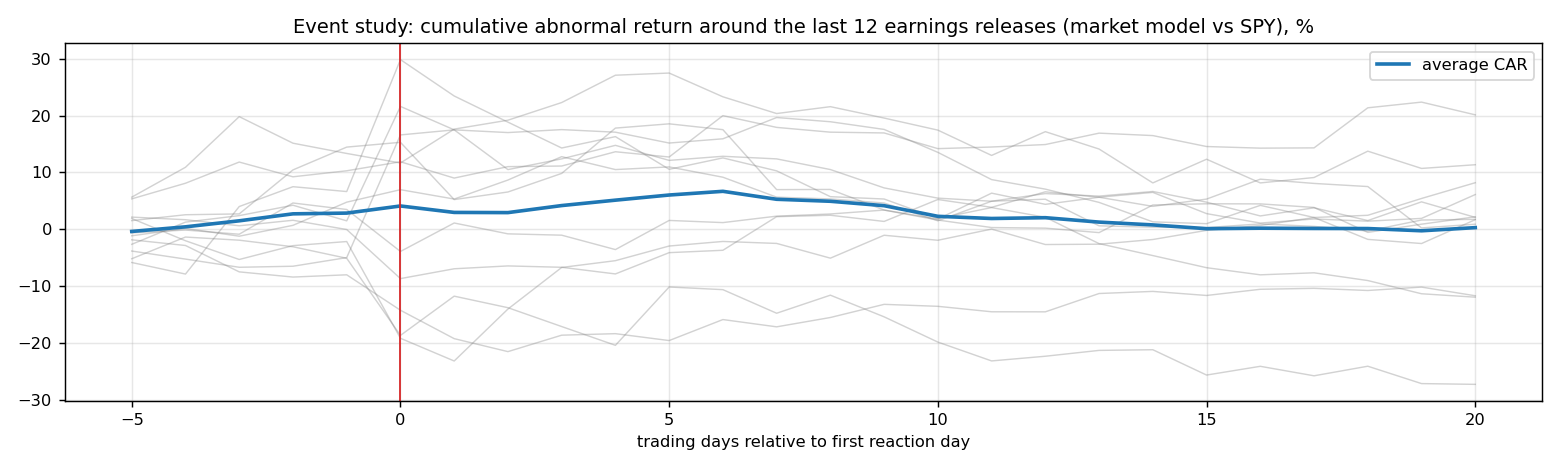
Market-model abnormal returns (vs SPY, estimated over the 250 days before each event) for the last 12 releases:
| Announced | Reaction day | EPS vs est. | Surprise | AR day 0 | CAR [−1,+1] | Drift CAR [+2,+20] |
|---|---|---|---|---|---|---|
| 2026-09-02 | 2026-09-03 | -0.20 vs -0.26 | 23.2% | +1.6% | -0.2% | +11.1% |
| 2026-06-03 | 2026-06-04 | -0.33 vs -0.37 | 11.5% | -1.7% | +2.5% | -6.3% |
| 2026-02-25 | 2026-02-26 | -0.40 vs -0.29 | -38.3% | -17.0% | -20.3% | +24.9% |
| 2025-12-03 | 2025-12-04 | -0.25 vs -0.33 | 24.8% | +2.2% | +4.6% | -3.6% |
| 2025-09-03 | 2025-09-04 | -0.37 vs -0.21 | -75.3% | -8.6% | -8.5% | +13.1% |
| 2025-05-28 | 2025-05-29 | -0.16 vs -0.20 | 20.4% | +20.1% | +13.3% | -15.4% |
| 2025-02-26 | 2025-02-27 | -0.12 vs -0.25 | 52.0% | -6.2% | -10.8% | +7.5% |
| 2024-12-09 | 2024-12-10 | -0.06 vs -0.16 | 62.9% | +0.8% | -5.2% | -4.3% |
| 2024-09-04 | 2024-09-05 | -0.05 vs -0.13 | 62.6% | -7.4% | -3.5% | +1.1% |
| 2024-05-29 | 2024-05-30 | -0.11 vs -0.30 | 63.7% | +21.6% | +24.0% | -9.3% |
| 2024-02-28 | 2024-02-29 | -0.13 vs -0.28 | 52.9% | +23.2% | +16.0% | -35.4% |
| 2023-12-06 | 2023-12-07 | -0.13 vs -0.18 | 29.5% | -13.6% | -8.7% | -15.5% |
- Average absolute day-0 abnormal move: 10.3%. The sign of the EPS surprise matched the sign of the reaction 67% of the time, which is close to a coin flip: guidance and commentary matter more than the headline EPS beat.
- Post-announcement drift: the correlation between the initial reaction and the next-20-day drift is -0.71. There is no reliable post-earnings drift, consistent with semi-strong efficiency.
8. Technicals and behavioural signals (ch.12)
| Indicator | Value | Read |
|---|---|---|
| Price vs 50-day / 200-day MA | +8% / +8% | Golden cross (50 > 200) |
| RSI(14) | 58 | Neutral |
| 12-1 month momentum | -40% | Negative (Jegadeesh-Titman) |
| 6-month relative strength vs XLK | -14% | Laggard |
| Insider sales / purchases, last 6m | USD 0.03bn / USD 0.00bn | Net selling, often planned 10b5-1 sales; insider buying is the informative signal (ch.11) |
| Analyst actions, last 90 days | 7 actions, 0 target raises | Few target raises: the Street is not chasing the stock |
| Recent targets below current price | 100% | Upside in the consensus has been used up |
| Ratings (strong buy / buy / hold / sell) | 0 / 0 / 7 / 6 | Mixed views: less crowded positioning |
| FY2028 EPS estimate: now vs 90 days ago | -0.48 vs -0.45 | +6% revision; up/down revisions in the last 30 days: 6/4 |
9. Treynor-Black: should an active manager overweight it? (ch.27)
| Step | Value |
|---|---|
| Analyst-implied 12m return (mean target / price − 1) | -25.2% |
| CAPM 1-year required return (raw β) | 15.5% |
| Raw alpha | -40.7% |
| Minus average analyst optimism bias (Top-30 cross-section) | -9.9% |
| Shrunk alpha (× 0.25, for forecast imprecision) | -12.7% |
| Residual variance σ²(e) | 76.9% |
| Initial active weight w₀ = [α/σ²(e)] / [E(R_M)/σ²_M] | -7.3% |
| Beta-adjusted weight w* = w₀ / [1 + (1 − β)w₀] | -6.8% |
A negative weight means an active manager would underweight it relative to the index.
10. Options market view (ch.20–21)
| Expiry | Days | ATM IV | Implied ±1σ move to expiry | 90% put − 110% call IV (skew) |
|---|---|---|---|---|
| 2026-10-16 | 11 | 53% | ±9.2% (±1.03) | -6.0% |
| 2026-10-23 | 18 | 65% | ±14.4% (±1.59) | +3.2% |
| 2026-10-30 | 25 | 58% | ±15.2% (±1.69) | -3.1% |
| 2026-11-06 | 32 | 64% | ±19.1% (±2.11) | -4.8% |
| 2026-11-20 | 46 | 57% | ±20.2% (±2.24) | -1.0% |
| 2026-12-18 | 74 | 66% | ±29.9% (±3.32) | -5.3% |
| 2027-01-15 | 102 | 63% | ±33.5% (±3.71) | -2.3% |
| 2027-03-19 | 165 | 67% | ±45.1% (±5.00) | -2.2% |
| 2027-04-16 | 193 | 70% | ±51.0% (±5.65) | +0.9% |
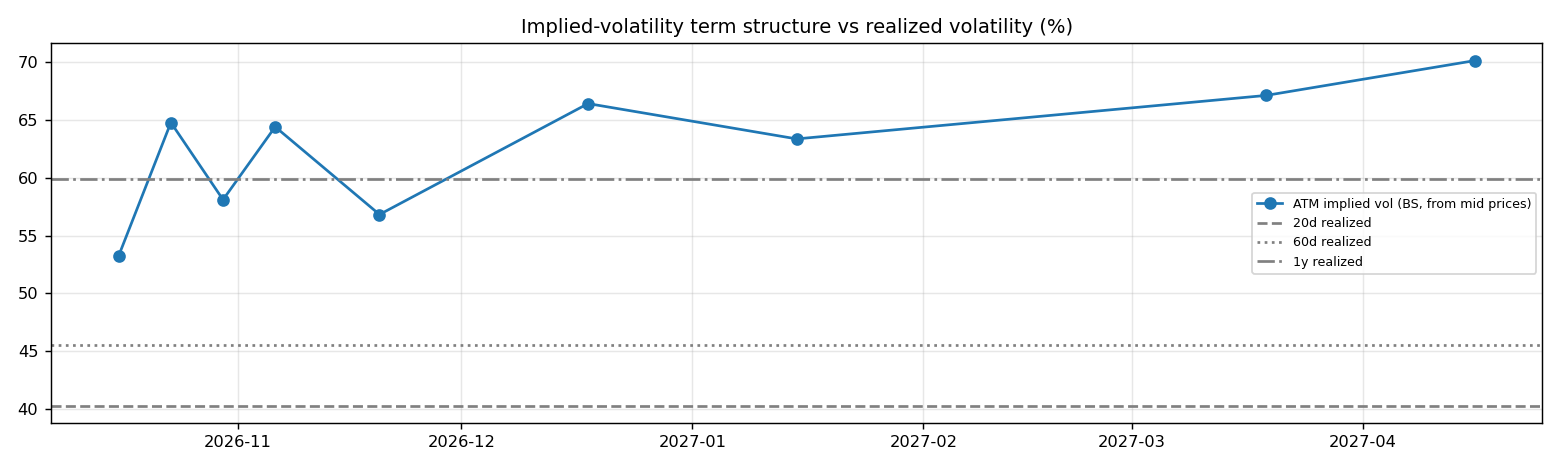
| - Implied vs realized: the ~1-month ATM IV is 64% vs realized 40% (20d) / 46% (60d) / 60% (1y). Options are rich relative to realized volatility, which favours premium sellers (covered calls, cash-secured puts). | ||||
| - Put-call parity (ch.20): at the ATM strike for 2026-11-06, C − P − (S − PV(K)) = -0.01 per share. Close to zero, as parity requires. | ||||
| - Quotes were unavailable when the data was pulled (outside market hours), so implied vols use each contract's last trade price. Treat them as approximate; illiquid strikes can be stale. |
Premium-selling menu for holders: the expiry closest to 35 days (2026-11-06), about 0.15/0.20/0.25/0.30 delta.
| Type | Strike | Bid / Ask | Price | IV | Delta | P(expires OTM) | Distance | Yield | Annualized | OI |
|---|---|---|---|---|---|---|---|---|---|---|
| Call | 12.5 | – | 0.31 | 59% | +0.28 | 77% | +12.7% | 2.80% | 32% | – |
| Call | 13.0 | – | 0.20 | 58% | +0.20 | 84% | +17.2% | 1.80% | 21% | – |
| Call | 13.5 | – | 0.13 | 57% | +0.15 | 89% | +21.7% | 1.17% | 13% | – |
| Put | 9.0 | – | 0.26 | 83% | -0.16 | 77% | -18.8% | 2.89% | 33% | – |
| Put | 10.0 | – | 0.31 | 60% | -0.24 | 70% | -9.8% | 3.10% | 35% | – |
Calls = covered calls on shares you own (yield on the share price); puts = cash-secured puts (yield on the strike). Prices are last trades at the data pull and indicative only; check live quotes before trading.
11. Our hourly signal model
AI is not in the Top-30 signal universe.
12. Qualitative analysis: business, PEST, catalysts and risks
Qualitative notes reviewed 2026-10-06
These notes are written by hand, unlike the auto-refreshed numbers above. Events up to late 2025 come from company announcements. Later developments are inferred from the data (consensus estimates, price reactions) and should be checked against AI's 10-Q/10-K filings and earnings calls.
Business in one paragraph
C3.ai sells enterprise AI applications, a development platform and generative-AI tools for industries such as energy, manufacturing, defense, financial services, utilities and state/local government. Revenue is mostly subscription and consumption-oriented software plus professional services, supported by go-to-market alliances with Microsoft, AWS, Google Cloud, Baker Hughes and systems integrators. The company has meaningful cash, but it is still loss-making and must prove that pilot activity converts into durable production contracts. The investment case hinges on whether generative AI demand revives growth while management narrows losses without overusing stock compensation or diluting shareholders.
Key developments
| When | Event | Why it matters |
|---|---|---|
| 2024 | C3.ai expanded strategic alliances with major cloud and consulting partners. | Partner-led selling is crucial because C3.ai competes with both cloud-native tools and internal customer teams. |
| Nov 2024 | C3.ai and Microsoft announced an expanded strategic alliance around enterprise AI on Azure. | Microsoft reach can lower sales friction, but it also makes execution dependent on partner prioritization. |
| FY2025 | C3.ai reported record fiscal-year revenue and ended the year with a large cash and investments balance. | Cash runway is not the immediate issue; converting growth to profitability is. |
| FY2025 | Baker Hughes relationship was renewed and expanded through June 2028. | Reduces uncertainty around a historically important energy partner. |
| 2025 | Management guided for continued growth and targeted a path toward profitability. | Investors need proof that sales efficiency improves after years of losses. |
PEST analysis
| Factor | Tailwinds | Headwinds | Net |
|---|---|---|---|
| Political | Defense, intelligence, energy-security and public-sector AI use cases support demand. | Public-sector procurement is slow; AI regulation, data residency and model-risk rules can delay deployments. | ⚖️ |
| Economic | Enterprises are budgeting for AI productivity tools, and C3.ai has cash to invest through cycles. | Customers scrutinize AI ROI; losses, stock compensation and potential future dilution remain concerns. | ⚠️ |
| Social | Boards want visible AI initiatives, and C3.ai benefits from a recognizable ticker and brand. | Buyers may prefer embedded AI from Microsoft, Salesforce, ServiceNow or internal teams rather than a separate platform. | ⚖️ |
| Technological | Prebuilt industry applications, model-agnostic architecture and cloud partnerships can shorten deployment time. | Foundation-model providers and hyperscalers move quickly; differentiation can erode if applications become easy to build. | ⚖️ |
Bull case vs bear case
- Bull: Generative AI pulls more customers from pilots to production, Microsoft and Baker Hughes drive larger deals, and operating discipline narrows losses while cash remains ample. C3.ai then becomes a specialized enterprise AI applications vendor rather than a perpetual proof-of-concept business.
- Bear: Revenue growth slows as customers consolidate on hyperscaler tools, services needs keep margins from scaling, and profitability targets slip. Cash runway helps, but dilution and stock compensation can still limit per-share upside if losses persist.
Catalysts to watch (next 6–12 months)
- Quarterly bookings, remaining performance obligations and pilot-to-production conversion.
- Operating-loss trajectory and cash burn after any restructuring or sales changes.
- Microsoft, Baker Hughes and federal deal activity.
- Customer concentration and churn indicators.
- Evidence that generative-AI products carry better margins than services-heavy deployments.
What would change the verdict
- More constructive: accelerating subscription growth, larger production deployments, lower sales friction through partners and a credible route to breakeven without dilution.
- More cautious: guide-downs, management turnover, rising services mix, persistent cash burn or signs that hyperscaler-native AI tools are displacing C3.ai projects.
Generated by analyses/deep-dives/deep_dive.py. Quantitative sections refresh weekly; the qualitative notes carry their own review date.