Rivian Automotive (RIVN) — Deep Dive
Prices as of the Mon 05 Oct 2026 close · data pulled 2026-10-06 07:31:00+00:00 · refreshed weekly · methodology
Not investment advice
Educational analysis built from public data (Yahoo Finance, Kenneth French Data Library) and explicit model assumptions. Numbers update automatically; the qualitative notes are dated.
Verdict: Reduce / Avoid — 3/8 checks pass
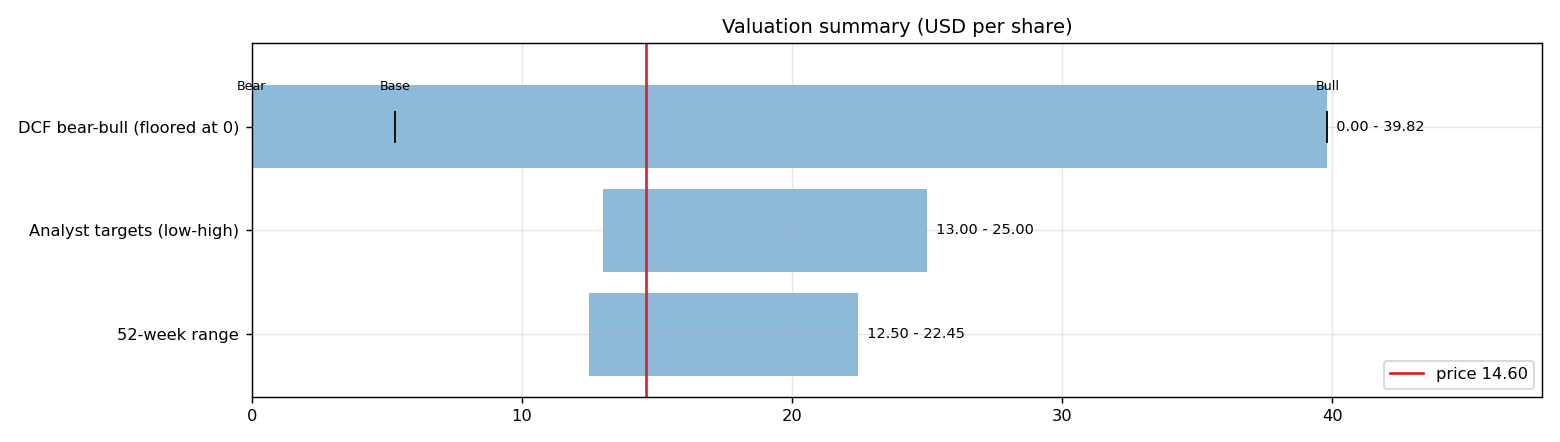
Rivian Automotive is not yet free-cash-flow positive after stock compensation, with net debt of USD 0.0bn and consensus revenue of 7.4bn for FY2026 and 11.7bn for FY2027 (+58%). At USD 14.60 the market prices in 44% a year revenue growth after FY2027 (fading to 4%) at a 8% owner-FCF margin, or a 11% margin on the base growth path. The base-case DCF is USD 5.30 (-64%). Cash runway at the current burn: about 1.5 years.
| Check | Pass | Evidence |
|---|---|---|
| Valuation: base-case DCF at or above price | ❌ | base DCF USD 5 vs price USD 15 |
| Relative value: forward P/E at most 1.2x the peer median | ❌ | n/m FY2027E vs peer median 16.6x |
| Street: de-biased, shrunk analyst alpha > 0 (ch27) | ✅ | +2.2% |
| Momentum: 12-1 month return > 0 (ch11) | ✅ | +18% |
| Trend: price above 200-day MA (ch12) | ❌ | -10% vs 200DMA |
| Not overbought: RSI(14) below 70 | ✅ | RSI 41 |
| Fundamentals: revenue growing and FCF positive | ❌ | revenue +27% y/y, TTM FCF -3.5bn |
| Balance sheet: net cash | ❌ | net cash -0.0bn |
Snapshot
| Metric | Value | Metric | Value |
|---|---|---|---|
| Price | USD 14.60 | Market cap | USD 21.1bn |
| Enterprise value | USD 21.1bn | Net cash | USD -0.0bn |
| 52-week range | 12.50 – 22.45 | From 52w high | -35.0% |
| Trailing P/E (GAAP) | n/m | Forward P/E FY2026 / FY2027 | n/m / n/m |
| PEG (FY+1 P/E ÷ EPS growth) | n/a | EV / TTM revenue | 3.6x |
| TTM revenue | USD 5.9bn | TTM FCF / after SBC | -3.5bn / -4.3bn |
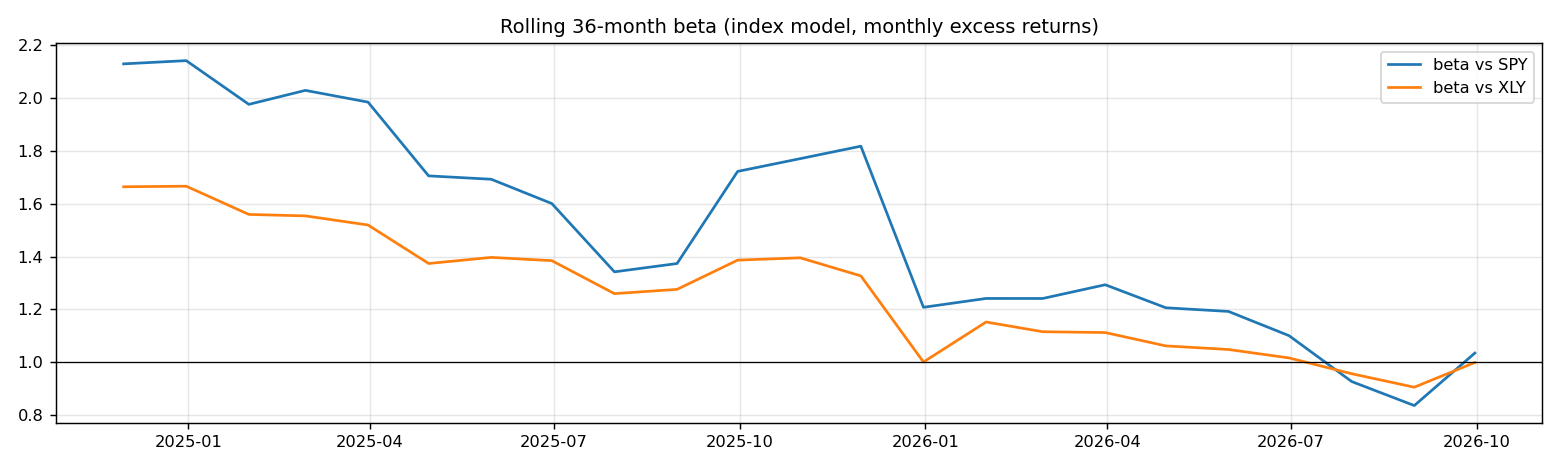
| Beta vs SPY (raw / Blume) | 1.61 / 1.41 | Realized vol 20d / 1y | 31% / 69% |
| Analysts / mean target | 26 / USD 19 (+31.7%) | Next earnings | 2026-10-29 |
| Shares out (diluted proxy) | 1.444bn | Short interest (% float) | 13.6% |
| Sector ETF benchmark | XLY | Cash runway (cash ÷ FCF burn) | 1.5 years |
| Institutions / insiders | 40% / 34.54% | Dividend | none |
1. Price over time
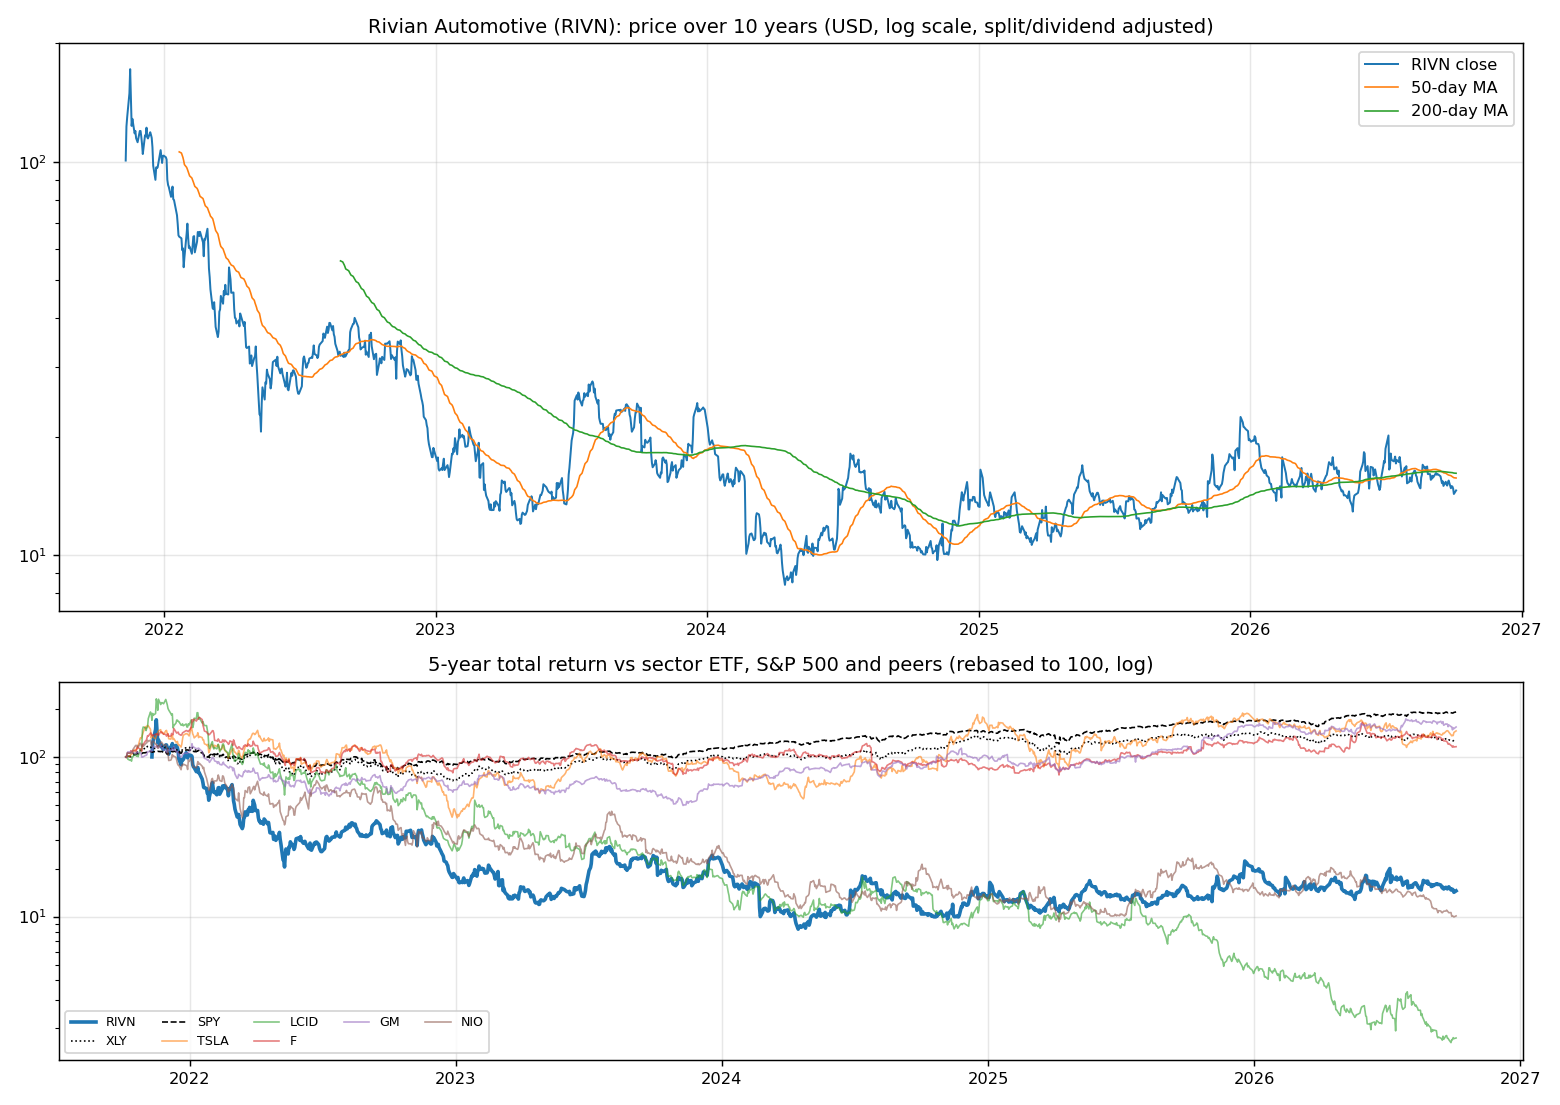
| Ticker | 1M | 3M | 6M | YTD | 1Y | 3Y | 5Y | 10Y | 10Y CAGR |
|---|---|---|---|---|---|---|---|---|---|
| RIVN | -7% | -28% | -5% | -26% | +7% | -23% | n/a | n/a | n/a |
| XLY | -4% | -6% | +2% | -7% | -6% | +41% | +28% | +206% | 11.8% |
| SPY | +1% | +3% | +18% | +15% | +17% | +87% | +91% | +321% | 15.5% |
| TSLA | +7% | -10% | +7% | -16% | -12% | +45% | +46% | +2625% | 39.2% |
| LCID | -11% | -37% | -55% | -61% | -83% | -92% | -98% | n/a | n/a |
| F | -17% | -11% | +7% | -4% | +0% | +22% | +16% | +65% | 5.1% |
| GM | -9% | +3% | +10% | -1% | +35% | +168% | +54% | +196% | 11.5% |
| NIO | -10% | -32% | -45% | -33% | -56% | -61% | -90% | n/a | n/a |
Largest one-day moves in the last 5 years: 22 Feb 2024 -25.6%, 05 Oct 2023 -22.9%, 13 Feb 2026 +26.6%, 09 May 2022 -20.9%, 03 Jan 2025 +24.5%.
2. Return and risk (ch.5)
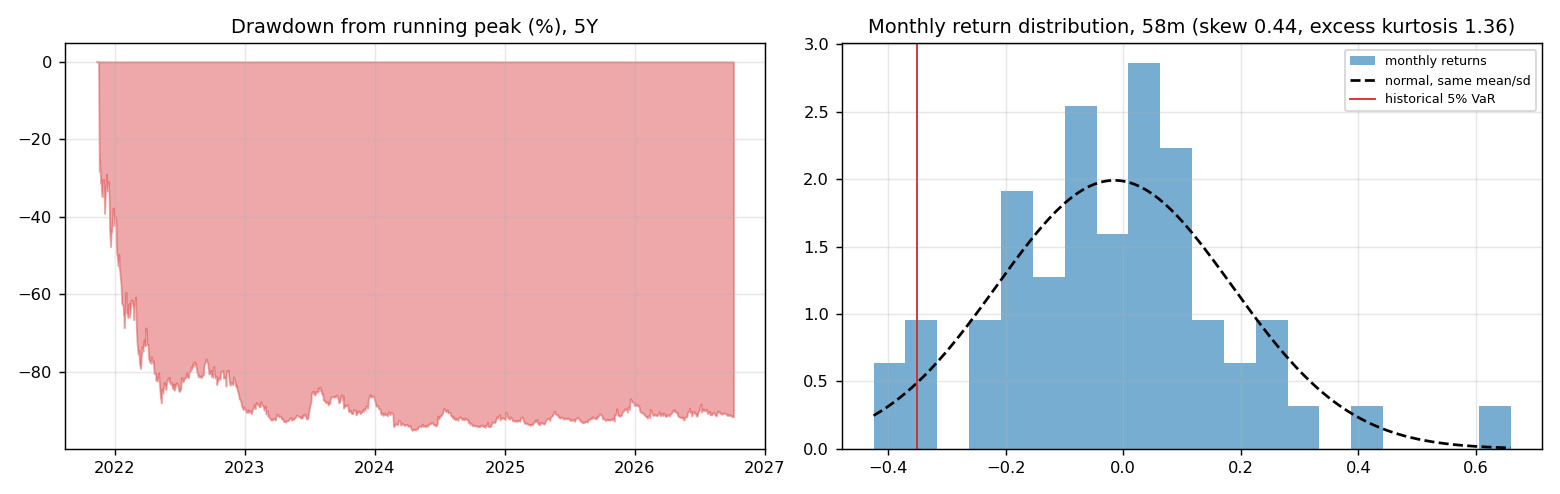
Statistics use the 58 complete months to Sep 2026.
| Statistic | Value | What it means |
|---|---|---|
| Arithmetic mean (annualized) | -18.1% | Expected one-period return if the past repeats |
| Geometric mean (CAGR) | -35.0% | What a buy-and-hold investor actually earned; the gap ≈ σ²/2 is volatility drag |
| Standard deviation (annualized) | 69.4% | 4.4× the S&P 500's 15.7% |
| Skewness / excess kurtosis | 0.44 / 1.36 | Right-skewed, fat tails vs normal |
| 5% monthly VaR: historical / normal | -35.0% / -34.5% | One month in 20 loses at least this much |
| 5% monthly expected shortfall | -39.6% | Average loss in that worst 5% of months |
| Sharpe ratio (S&P 500) | -0.32 (0.61) | Excess return per unit of total risk |
| Sortino ratio | -0.43 | Excess return per unit of downside risk |
| Max drawdown, 5y | -95.1% (trough Apr 2024) | Currently -91.5% from the peak |
3. Index model, CAPM and factors (ch.8–10)
| Regression (60m excess returns) | Alpha (ann.) | t(α) | Beta | t(β) | R² | Residual σ |
|---|---|---|---|---|---|---|
| vs SPY | -37.2% | -1.24 | 1.61 | 2.91 | 0.13 | 64.6% |
| vs XLY | -23.0% | -0.81 | 1.40 | 3.75 | 0.20 | 62.0% |
- Risk decomposition (ch.8): systematic variance β²σ²(M) = 6.4% vs firm-specific σ²(e) = 41.8%, so 13% of the risk is market-driven and 87% is diversifiable.
- CAPM required return (ch.9): k = r_f + β × MRP = 4.02% + 1.61 × 5.5% = 12.9% (Blume-adjusted β 1.41 → 11.8%, used as the DCF discount rate).
- Historical alpha of -37.2% a year has a t-stat of -1.24: not statistically distinguishable from zero (ch.11: past alpha is a weak guide).
- Fama-French 5 factors + momentum (ch.10, 56 months to Jul 2026): R² 0.46, alpha -29.0% (t -1.07). Loadings: Mkt-RF +1.13 (t 2.3), SMB +2.07 (t 2.4), HML +1.81 (t 2.0), RMW -0.27 (t -0.3), CMA -3.12 (t -2.8), Mom -0.70 (t -1.2). The loadings describe a small-cap, value, low-profitability return profile (SMB > 0 small-cap, HML < 0 growth, RMW < 0 weak profitability, CMA < 0 aggressive investment).
4. Portfolio fit: allocation and diversification (ch.6–7)
Correlation of monthly returns with RIVN (58m): XLY 0.45, SPY 0.37, TSLA 0.46, LCID 0.36, F 0.27, GM 0.38, NIO 0.31.
- A 50/50 mix with SPY would have had volatility of 38.3% vs 42.6% for the weighted average of the two, a diversification benefit because ρ = 0.37 < 1.
- Optimal risky share y* = [E(r) − r_f] / (A·σ²), holding RIVN alone against T-bills (σ = 69.4%):
| Risk aversion A | y* with CAPM E(r) | y* with E(r) + Street α |
|---|---|---|
| 2 | 9% | 12% |
| 3 | 6% | 8% |
| 4 | 5% | 6% |
| 6 | 3% | 4% |
Even a risk-tolerant investor would put only a modest share in a single stock this volatile. Ch.7–8 say the efficient choice is the market portfolio plus a Treynor-Black tilt (section 9), not a concentrated position.
5. Financial statements: quality of earnings (ch.19)
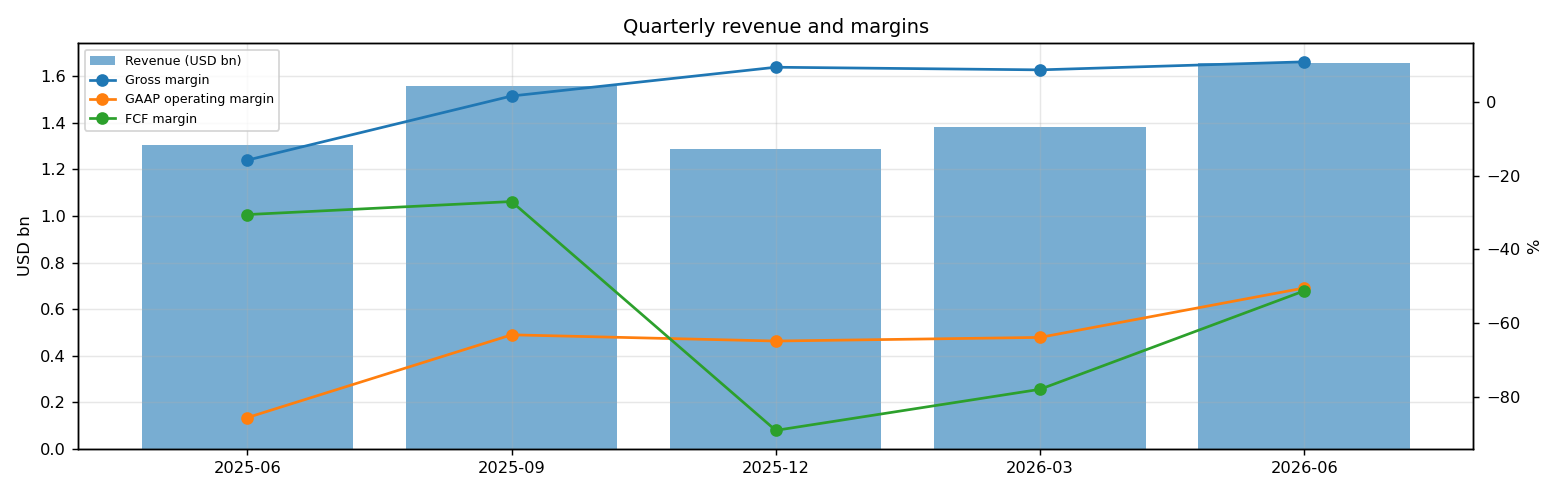
| Quarter | Revenue | Q/Q | Gross m. | Op. m. (GAAP) | Net m. | R&D % | SBC % | Diluted EPS | FCF | FCF m. | DSO (days) | DIO (days) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2025-06 | 1.3bn | n/a | -15.8% | -85.5% | -85.7% | 31.5% | 14.5% | -0.97 | -0.40bn | -30.5% | 18 | 127 |
| 2025-09 | 1.6bn | +20% | 1.5% | -63.1% | -75.3% | 29.1% | 11.2% | -0.96 | -0.42bn | -27.0% | 12 | 97 |
| 2025-12 | 1.3bn | -17% | 9.3% | -64.8% | -63.1% | 33.0% | 14.8% | -0.66 | -1.14bn | -89.0% | 39 | 124 |
| 2026-03 | 1.4bn | +7% | 8.6% | -63.8% | -30.1% | 33.2% | 15.0% | -0.33 | -1.07bn | -77.8% | 23 | 111 |
| 2026-06 | 1.7bn | +20% | 10.8% | -50.4% | -50.2% | 28.1% | 13.6% | -0.63 | -0.85bn | -51.2% | 20 | 102 |
- DuPont, TTM: ROE -64.1% = net margin -55.0% × asset turnover 0.39 × leverage 2.98. Net income is negative, so ROE is negative; the business is not yet earning its cost of equity.
- Cash conversion: TTM operating cash flow -1.8bn vs net income -3.2bn. The accruals ratio of -9.2% of assets is negative (cash earnings exceed accounting earnings), a sign of high-quality earnings.
- Stock-based compensation of 0.8bn TTM (13.5% of revenue) is a real cost to shareholders. The valuation below uses FCF after SBC (owner FCF margin -72.9%). Buybacks were n/a; share count changed +12.2% over the year.
- Operating leverage (ch.17): not meaningful: EBIT was negative or sales barely moved between the last two fiscal years.
6. Valuation (ch.18)
Multiples vs peers (Yahoo Finance, TTM and next-year; peers chosen by hand in config.json):
| Ticker | Fwd P/E | P/S TTM | EV/EBITDA | FCF yield | Rev. growth FY | Gross m. | EBIT m. | ROE TTM | Target upside |
|---|---|---|---|---|---|---|---|---|---|
| RIVN | -8.4x | 3.6x | -7.8x | -7% | 27% | 8% | -50% | -58% | 32% |
| TSLA | 176.6x | 14.4x | 136.6x | 0% | 26% | 19% | 1% | 5% | 5% |
| LCID | -0.8x | 1.1x | -2.1x | -207% | 56% | -101% | -261% | -126% | 91% |
| F | 6.2x | 0.3x | 24.8x | -16% | -4% | 7% | 2% | -18% | 32% |
| GM | 5.3x | 0.4x | 10.7x | 31% | 2% | 10% | 3% | 3% | 30% |
| NIO | 26.9x | 0.1x | 1.4x | n/a | 69% | 17% | -1% | -45% | 84% |
| Peer median | 6.2x | 0.4x | 10.7x | -8% | 26% | 10% | 1% | -18% | 32% |
Growth embedded in the price (PVGO). Next-year EPS is expected to be negative (USD -2.17), so the whole price is PVGO: it rests entirely on future profits that do not exist yet.
Constant-growth check. On TTM owner FCF, P = FCF₁/(k − g) implies a perpetual growth rate of 32.9%, above the 4% long-run nominal-GDP ceiling the book recommends for g.
Scenario DCF (owner FCF, k = 11.8%, terminal g = 4%). The revenue path is FY2026 (7.4bn), then the FY2027 low/avg/high estimate, then growth that fades linearly to 4% over 8 years. Owner-FCF margin ramps from today's -72.9% to the scenario margin over 5 years. Scenario assumptions are generic (derived from consensus growth and today's owner-FCF margin).
| Scenario | FY2027 revenue | Growth after | Owner-FCF margin | FY2035 revenue | Terminal value share | Value / share | vs price |
|---|---|---|---|---|---|---|---|
| Bear | 8.9bn | 15% | 3% | 19bn | n/a | USD -5.31 | -136% |
| Base | 11.7bn | 30% | 8% | 45bn | 224% | USD 5.30 | -64% |
| Bull | 17.7bn | 40% | 12% | 98bn | 104% | USD 39.82 | +173% |
Reverse DCF: what today's price assumes. On the base revenue path the price requires a steady-state owner-FCF margin of 11%. At the base 8% margin it requires 44% growth after FY2027, or a discount rate of 9.4% (vs the model's 11.8%).
Sensitivity: base revenue path, value per share by discount rate (rows) and steady-state owner-FCF margin (columns).
| k \ margin | 4% | 6% | 7% | 9% | 10% |
|---|---|---|---|---|---|
| 8.8% | 3.60 | 12.08 | 16.31 | 24.79 | 29.02 |
| 9.8% | 0.51 | 7.32 | 10.73 | 17.54 | 20.95 |
| 10.8% | -1.59 | 4.06 | 6.89 | 12.54 | 15.36 |
| 11.8% | -3.09 | 1.71 | 4.10 | 8.90 | 11.30 |
| 12.8% | -4.19 | -0.05 | 2.02 | 6.16 | 8.23 |
| ## 7. Market efficiency and earnings reactions (ch.11) |
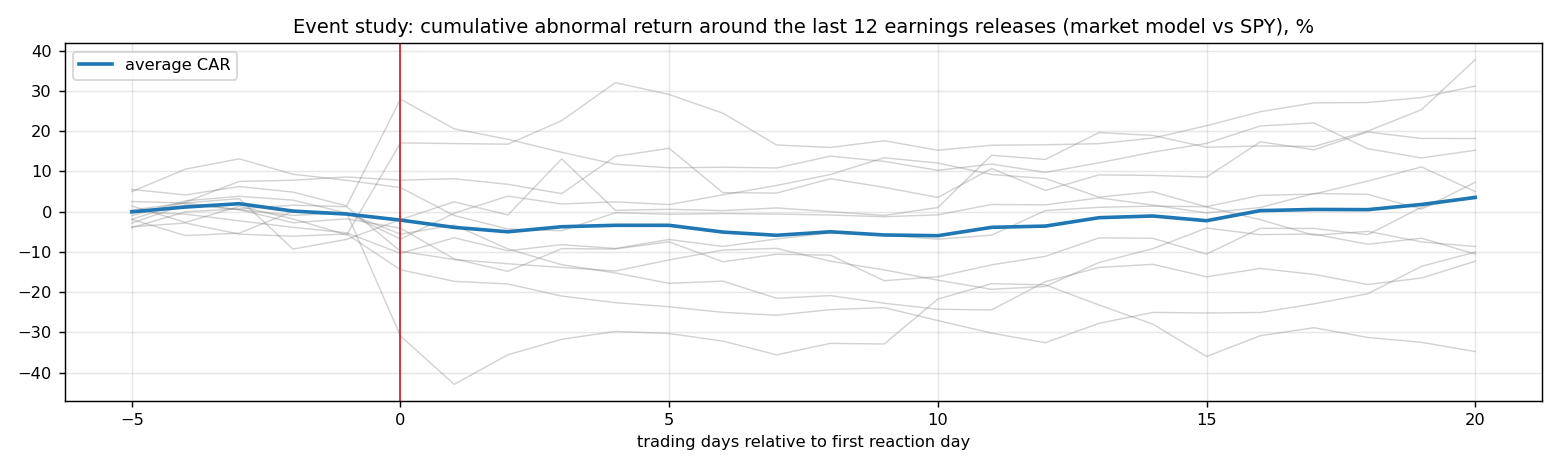
Market-model abnormal returns (vs SPY, estimated over the 250 days before each event) for the last 12 releases:
| Announced | Reaction day | EPS vs est. | Surprise | AR day 0 | CAR [−1,+1] | Drift CAR [+2,+20] |
|---|---|---|---|---|---|---|
| 2026-07-30 | 2026-07-31 | -0.63 vs -0.78 | 18.9% | -11.1% | -13.5% | +1.4% |
| 2026-04-30 | 2026-05-01 | -0.33 vs -0.72 | 53.9% | -8.9% | -11.2% | +7.3% |
| 2026-02-12 | 2026-02-13 | -0.66 vs -0.79 | 16.6% | +26.5% | +15.7% | -5.3% |
| 2025-11-04 | 2025-11-05 | -0.96 vs -0.86 | -11.1% | +22.9% | +18.7% | +14.3% |
| 2025-08-05 | 2025-08-06 | -0.97 vs -0.78 | -24.7% | -5.1% | -2.6% | +11.5% |
| 2025-05-06 | 2025-05-07 | -0.41 vs -0.74 | 44.1% | -6.5% | +0.5% | -8.3% |
| 2025-02-20 | 2025-02-21 | -0.70 vs -0.77 | 9.6% | -1.8% | -10.3% | +8.3% |
| 2024-11-07 | 2024-11-08 | -1.08 vs -1.09 | 0.9% | +4.9% | +11.7% | +35.3% |
| 2024-08-06 | 2024-08-07 | -1.46 vs -1.41 | -3.8% | -5.3% | -3.4% | -9.0% |
| 2024-05-06 | 2024-05-07 | -1.48 vs -1.27 | -16.1% | -0.8% | +0.4% | +10.0% |
| 2024-02-21 | 2024-02-22 | -1.36 vs -1.32 | -3.4% | -30.5% | -45.8% | +8.1% |
| 2023-11-07 | 2023-11-08 | -1.19 vs -1.32 | 10.1% | -2.3% | -9.0% | +15.7% |
- Average absolute day-0 abnormal move: 10.5%. The sign of the EPS surprise matched the sign of the reaction 50% of the time, which is close to a coin flip: guidance and commentary matter more than the headline EPS beat.
- Post-announcement drift: the correlation between the initial reaction and the next-20-day drift is 0.12. There is no reliable post-earnings drift, consistent with semi-strong efficiency.
8. Technicals and behavioural signals (ch.12)
| Indicator | Value | Read |
|---|---|---|
| Price vs 50-day / 200-day MA | -7% / -10% | Death cross (50 < 200) |
| RSI(14) | 41 | Neutral |
| 12-1 month momentum | +18% | Positive (Jegadeesh-Titman) |
| 6-month relative strength vs XLY | -6% | Laggard |
| Insider sales / purchases, last 6m | USD 0.00bn / USD 1.00bn | Net insider buying: an informative signal (ch.11) |
| Analyst actions, last 90 days | 12 actions, 9 target raises | Targets chasing the price is a sign of anchoring and herding (ch.12) |
| Recent targets below current price | 17% | Most targets still sit above the price |
| Ratings (strong buy / buy / hold / sell) | 5 / 8 / 8 / 5 | Mixed views: less crowded positioning |
| FY2027 EPS estimate: now vs 90 days ago | -2.17 vs -2.40 | -9% revision; up/down revisions in the last 30 days: 2/2 |
9. Treynor-Black: should an active manager overweight it? (ch.27)
| Step | Value |
|---|---|
| Analyst-implied 12m return (mean target / price − 1) | +31.7% |
| CAPM 1-year required return (raw β) | 12.9% |
| Raw alpha | +18.8% |
| Minus average analyst optimism bias (Top-30 cross-section) | -9.9% |
| Shrunk alpha (× 0.25, for forecast imprecision) | +2.2% |
| Residual variance σ²(e) | 41.8% |
| Initial active weight w₀ = [α/σ²(e)] / [E(R_M)/σ²_M] | +2.4% |
| Beta-adjusted weight w* = w₀ / [1 + (1 − β)w₀] | +2.4% |
A positive weight means an active manager would hold more than its index weight.
10. Options market view (ch.20–21)
| Expiry | Days | ATM IV | Implied ±1σ move to expiry | 90% put − 110% call IV (skew) |
|---|---|---|---|---|
| 2026-10-16 | 11 | 56% | ±9.7% (±1.42) | -3.6% |
| 2026-10-23 | 18 | 53% | ±11.8% (±1.72) | +2.2% |
| 2026-10-30 | 25 | 68% | ±17.8% (±2.59) | +1.8% |
| 2026-11-06 | 32 | 64% | ±18.9% (±2.76) | -2.3% |
| 2026-11-13 | 39 | 64% | ±20.8% (±3.04) | +5.0% |
| 2026-11-20 | 46 | 62% | ±21.9% (±3.20) | +3.4% |
| 2026-12-18 | 74 | 58% | ±26.3% (±3.84) | +0.4% |
| 2027-01-15 | 102 | 59% | ±31.4% (±4.59) | +3.4% |
| 2027-03-19 | 165 | 62% | ±41.4% (±6.04) | +6.5% |
| 2027-06-17 | 255 | 65% | ±54.0% (±7.88) | +2.1% |
| 2027-09-17 | 347 | 63% | ±61.9% (±9.03) | +1.5% |
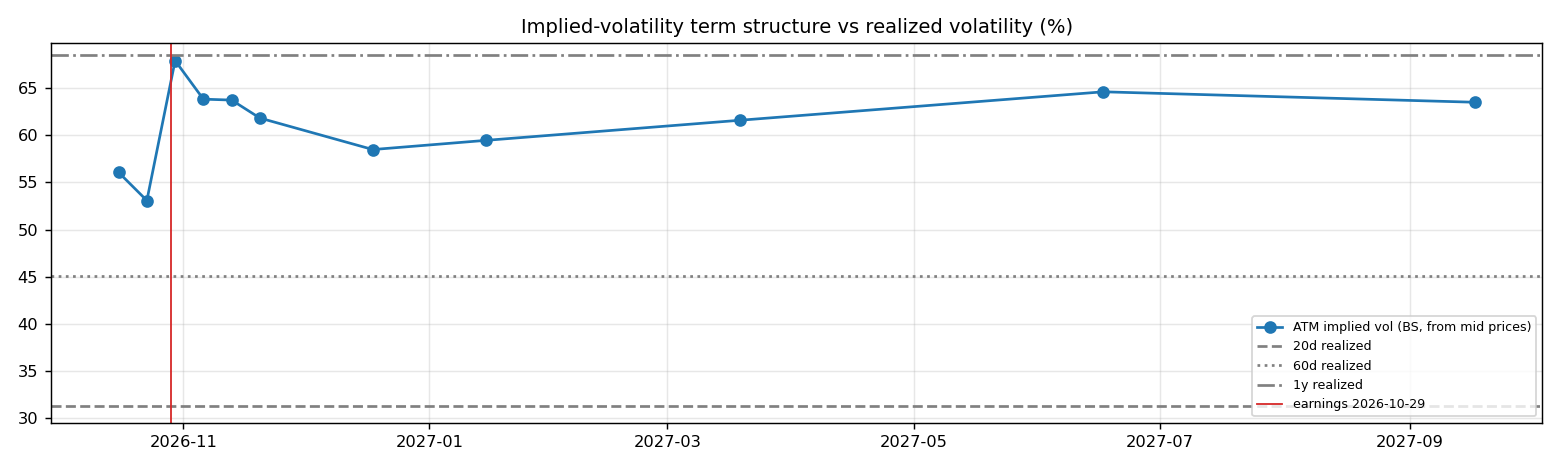
- Earnings-implied move: the jump in variance from the 2026-10-23 expiry (IV 53%) to 2026-11-06 (IV 64%) prices an earnings-day move of ±10.5% (1σ), or about ±8.4% in absolute terms (≈ ±1.22). Compare the historical average absolute reaction of 10.5% in section 7.
- Implied vs realized: the ~1-month ATM IV is 64% vs realized 31% (20d) / 45% (60d) / 69% (1y). Options are rich relative to realized volatility, which favours premium sellers (covered calls, cash-secured puts).
- Put-call parity (ch.20): at the ATM strike for 2026-11-06, C − P − (S − PV(K)) = -0.10 per share. Close to zero, as parity requires.
- Quotes were unavailable when the data was pulled (outside market hours), so implied vols use each contract's last trade price. Treat them as approximate; illiquid strikes can be stale.
Premium-selling menu for holders: the last expiry before earnings (2026-10-23), about 0.15/0.20/0.25/0.30 delta.
| Type | Strike | Bid / Ask | Price | IV | Delta | P(expires OTM) | Distance | Yield | Annualized | OI |
|---|---|---|---|---|---|---|---|---|---|---|
| Call | 16.0 | – | 0.23 | 53% | +0.24 | 79% | +9.6% | 1.58% | 32% | – |
| Call | 17.0 | – | 0.11 | 56% | +0.13 | 90% | +16.4% | 0.75% | 15% | – |
| Call | 25 | – | 0.71 | 229% | +0.21 | 90% | +71.2% | 4.86% | 99% | – |
| Put | 13.0 | – | 0.15 | 55% | -0.15 | 82% | -11.0% | 1.15% | 23% | – |
| Put | 13.5 | – | 0.26 | 55% | -0.24 | 73% | -7.5% | 1.93% | 39% | – |
Calls = covered calls on shares you own (yield on the share price); puts = cash-secured puts (yield on the strike). Prices are last trades at the data pull and indicative only; check live quotes before trading.
11. Our hourly signal model
RIVN is not in the Top-30 signal universe.
12. Qualitative analysis: business, PEST, catalysts and risks
Qualitative notes reviewed 2026-10-06
These notes are written by hand, unlike the auto-refreshed numbers above. Events up to late 2025 come from company announcements. Later developments are inferred from the data (consensus estimates, price reactions) and should be checked against RIVN's 10-Q/10-K filings and earnings calls.
Business in one paragraph
Rivian makes electric adventure vehicles, commercial vans and vehicle software. Current revenue comes from R1T pickups, R1S SUVs, electric delivery vans for Amazon and other fleets, services, regulatory credits and, increasingly, technology collaboration with Volkswagen. The future case is about the lower-cost R2 and R3 families, a simpler bill of materials, higher plant utilization in Normal, Illinois, and eventually the Georgia site. Rivian has a respected brand and strong product reviews, but remains cash-burning. The investment case hinges on whether it can bridge to R2 launch without excessive dilution and then scale profitably in a crowded EV market.
Key developments
| When | Event | Why it matters |
|---|---|---|
| Mar 2024 | Rivian unveiled R2, R3 and R3X, and chose to start R2 production in Illinois before Georgia. | Pulled forward a lower-cost platform and reduced near-term capital needs. |
| Jun-Nov 2024 | Volkswagen and Rivian announced and then launched a joint venture valued at up to USD 5.8bn. | Added capital, validated Rivian's software/electrical architecture and created a potential licensing revenue path. |
| Q4 2024 | Rivian achieved a modest gross profit for the first time. | Showed cost reductions can work, though sustained profitability still depends on volume and R2. |
| 2024-2025 | DOE financing and state support remained tied to the Georgia factory plan. | Lowers funding risk for long-term capacity, but the plant adds execution complexity. |
| Sep 2025 | Rivian held a Georgia plant kickoff ceremony (reported). | Signaled commitment to future R2/R3 expansion after the initial Normal ramp. |
PEST analysis
| Factor | Tailwinds | Headwinds | Net |
|---|---|---|---|
| Political | US EV manufacturing loans, domestic battery policy and fleet decarbonization support demand and capacity. | EV tax-credit rules, tariffs and changing climate policy can alter affordability and supply costs. | ⚖️ |
| Economic | R2 targets a broader price band, and the VW deal reduces capital strain. Amazon fleet demand can smooth cycles. | Rivian still burns cash, carries launch risk and may need more capital if R2 slips or macro demand weakens. | ⚠️ |
| Social | Strong owner community, outdoor brand identity and high satisfaction with R1 vehicles. | The addressable audience for premium adventure EVs is narrower than mainstream SUVs; charging and repair anxiety persist. | ⚖️ |
| Technological | In-house software, zonal architecture, over-the-air updates and vehicle packaging attracted Volkswagen. | Battery cost, manufacturing yield and software reliability must improve at much higher volume; Tesla and Chinese EV makers set tough benchmarks. | ✅ |
Bull case vs bear case
- Bull: R2 launches on time with lower build cost, VW funding and licensing reduce dilution, and Rivian turns gross profit into operating leverage. The brand then expands from premium adventure vehicles into a credible mass-market SUV franchise.
- Bear: R2 timing slips, launch costs exceed plan, EV demand softens, and cash burn remains high enough to require more equity before profitability. VW collaboration may help technology but cannot fix manufacturing economics if volumes disappoint.
Catalysts to watch (next 6–12 months)
- R2 validation, tooling progress and supplier readiness before launch.
- Quarterly cash burn, liquidity and any additional capital actions.
- Gross margin excluding regulatory credits and launch costs.
- Volkswagen JV milestones, software integration and any third-party licensing interest.
- Amazon and non-Amazon van orders as evidence of commercial-fleet diversification.
What would change the verdict
- More constructive: R2 launches on schedule with strong reservations, gross margin stays positive through ramp preparation, and VW milestones arrive without major cash needs.
- More cautious: R2 delays, renewed negative gross margins, rising warranty issues, or financing that materially dilutes existing holders.
Generated by analyses/deep-dives/deep_dive.py. Quantitative sections refresh weekly; the qualitative notes carry their own review date.